
NRI Buying Property in Kolkata: What Actually Applies to You
Buying from abroad is not harder than buying from Salt Lake. It is different in four specific ways, and almost every difficulty NRIs run into traces back to one of them. Nobody explains this well, largely because most guides are written to collect enquiries rather than to be useful.
Here is what genuinely applies to an NRI buying property in Kolkata, and what does not.
What you are allowed to buy
An NRI may purchase residential and commercial property in India without needing permission for each transaction. That covers everything most buyers want: a flat, a villa, an office.
What you may not purchase is agricultural land, plantation property or a farmhouse. This catches people out in the corridors around Kolkata, where a plot that looks like an ordinary building site can still be classified as agricultural on the land record. If you are looking at land rather than an apartment, establish the classification on the parcha before anything else. Our guide to parcha, mutation and khajna explains where that sits.
You can, however, inherit agricultural land, and you can continue to hold what you inherited. The restriction is on purchase.
How the money has to move
Payment must come through normal banking channels: an inward remittance, or funds held in your NRE, NRO or FCNR account. Payment in foreign currency handed over in India, or through a third party's account, is not acceptable and creates problems that are tedious to unwind later.
The practical consequence is timing. Remittances take days rather than minutes, and booking windows in a hot project sometimes do not wait. If you are shortlisting seriously, have funds positioned in an Indian account before you need them rather than after.
The tax point most NRIs discover too late
When you eventually sell, the buyer is required to deduct TDS from the payment to you, and the rate applied to an NRI seller is significantly higher than the rate applied to a resident. That is not a tax on the gain, it is a deduction on the consideration, and reclaiming any excess means filing a return and waiting.
There is a mechanism to reduce it. You can apply for a lower deduction certificate from the tax authorities, based on your actual expected gain rather than the headline value. It requires paperwork and lead time, which is why it needs to be started well before the sale rather than during it.
The reason to understand this at purchase, not at sale, is that it shapes how you should hold the property and what records you need to keep from day one. Keep every payment receipt, the registered deed, and evidence of any improvement expenditure. Those documents establish your cost base years later.
Repatriating the proceeds
Sale proceeds can generally be repatriated, subject to limits and conditions and provided the original purchase was made through proper banking channels. Property acquired with funds from an NRE account is treated more favourably on repatriation than property acquired through an NRO account.
This is a strong argument for thinking about the exit at the point of entry. Which account you buy through affects how easily the money comes back out, and that decision is made once, at the beginning, and cannot be retrofitted.
Running a purchase from eight time zones away
The single most useful thing you can do is execute a properly drafted power of attorney in favour of someone you trust in India. It must be executed and attested correctly from abroad, usually through the Indian mission in your country, and then adjudicated in India. Doing it badly is worse than not doing it, because a defective POA is discovered at the registration counter.
Keep the scope narrow and specific. A POA for a defined transaction on a defined property is appropriate. A general POA handing over broad authority is not, and no reputable advisor will suggest one.
Beyond that, insist on documentation rather than reassurance. Ask for the RERA registration number and check it yourself on the state portal, which takes two minutes from anywhere in the world. Our guide to verifying a RERA number in West Bengal covers the phase-specific check that matters most.
What the purchase actually costs you
The statutory costs are the same for you as for a resident. In Kolkata and Howrah Corporation areas, stamp duty is 6% of assessed value below ₹1 crore and 7% above, plus 1% registration, plus a further 1% additional duty above the threshold. That threshold matters more to NRI buyers than to most, because the budgets involved often sit near it. Our stamp duty guide reproduces the current government table, and flats in Kolkata under ₹1 crore covers staying the right side of it.
Where NRI buyers in Kolkata tend to look
Two patterns dominate. Buyers with family in the city usually want something in the established south, where the address matters and supply is finite. Godrej Blue New Alipore from ₹2.53 Cr and Morya New Alipore from ₹1.75 Cr sit in that category.
Buyers treating it as an investment tend toward the employment-led corridors, where tenant demand is deepest and management is simplest. DTC Downtown Rajarhat from ₹63 L and Vinayak 21 Acres New Town from ₹71 L are the usual shortlist, with Kolkata's rental yield running near 4.13%.
Our guide to the best areas to buy a flat in Kolkata sets out which driver is behind each corridor, which matters more when you cannot visit often.
A realistic sequence
Establish your banking route first, then your POA if you need one, then shortlist, then verify RERA registration yourself, then remit. Buyers who do it in that order rarely have problems. Buyers who fall for a flat first and sort out the mechanics afterwards almost always do.
We will send you documentation, floor plans and video walkthroughs before you travel, and arrange viewings in a single visit when you do. Start with buy a home, browse verified properties, or talk to our legal and loan help desk.
We are a RERA-registered agent, WBRERA/A/HOW/2025/000651. This is general guidance, not tax or legal advice. Rules for NRIs change and depend on your residency status, so take professional advice on your own position before you transact.
What NRI buyers usually shortlist with us
Buying from abroad means you are picking on paper, so a named developer and a clean RERA filing carry more weight than usual.
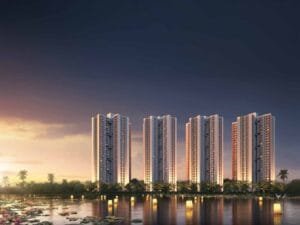
Sansara, Howrah — 3, 4 and 5 BHK from ₹3.20 Cr. Sansara is PS Group, five towers at G+40 on the riverfront.
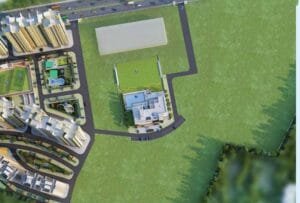
Emami Aastha, Joka — 3.5, 4.5 and 5.5 BHK bungalows from ₹1.31 Cr. Emami Aastha is an independent house on its own plot inside a gated 40-acre township (WBRERA/P/SOU/2023/000507), which is what most NRI buyers are actually after when they say they do not want a flat.
Keep reading
Every buying guide we have written
Twenty-seven guides on buying in Kolkata, written from real prices and real projects. Take your pick.
 Investing & RentingCommercial Property in Kolkata
 LocalitiesReal Estate Developers in Kolkata
 Legal & LoansBuying Land in Howrah or Hooghly
 Investing & RentingHow to Rent Out Your Flat in Kolkata
 Buying GuidesFirst Time Home Buyer in Kolkata
 Buying GuidesBuying a Resale Flat in Kolkata
 Buying GuidesVastu Tips for Buying a Flat
 Investing & RentingRental Yield in Kolkata
 LocalitiesFlats in New Alipore & Tollygunge
 Investing & RentingKolkata Property Price Trends 2026
 LocalitiesBest Areas to Buy a Flat in Kolkata
 Buying GuidesFlats in Kolkata Under ₹1 Crore
 LocalitiesFlats in Behala on the Purple LineInvesting & RentingCommercial Property in KolkataLocalitiesReal Estate Developers in KolkataLegal & LoansBuying Land in Howrah or HooghlyInvesting & RentingHow to Rent Out Your Flat in KolkataBuying GuidesFirst Time Home Buyer in KolkataBuying GuidesBuying a Resale Flat in KolkataBuying GuidesVastu Tips for Buying a FlatInvesting & RentingRental Yield in KolkataLocalitiesFlats in New Alipore & TollygungeInvesting & RentingKolkata Property Price Trends 2026LocalitiesBest Areas to Buy a Flat in KolkataBuying GuidesFlats in Kolkata Under ₹1 CroreLocalitiesFlats in Behala on the Purple Line
 Legal & LoansStamp Duty in West Bengal 2026
 Buying Guides2 BHK or 3 BHK in Kolkata?
 LocalitiesProperty in Howrah, Pocket by Pocket
 LocalitiesFlats Near Metro Stations in Kolkata
 Legal & LoansParcha, Mutation & Khajna Explained
 Legal & LoansHome Loan in Kolkata: Eligibility & EMI
 LocalitiesNew Town vs Rajarhat vs Salt Lake
 Buying GuidesFlats in Kolkata Under ₹60 Lakh
 Buying GuidesUnder Construction vs Ready to Move
 Legal & LoansWhat a Kolkata Flat Really Costs
 LocalitiesFlats in Joka After the Metro
 Legal & LoansHow to Verify a RERA Number
 LocalitiesProperty in UttarparaLegal & LoansStamp Duty in West Bengal 2026Buying Guides2 BHK or 3 BHK in Kolkata?LocalitiesProperty in Howrah, Pocket by PocketLocalitiesFlats Near Metro Stations in KolkataLegal & LoansParcha, Mutation & Khajna ExplainedLegal & LoansHome Loan in Kolkata: Eligibility & EMILocalitiesNew Town vs Rajarhat vs Salt LakeBuying GuidesFlats in Kolkata Under ₹60 LakhBuying GuidesUnder Construction vs Ready to MoveLegal & LoansWhat a Kolkata Flat Really CostsLocalitiesFlats in Joka After the MetroLegal & LoansHow to Verify a RERA NumberLocalitiesProperty in Uttarpara